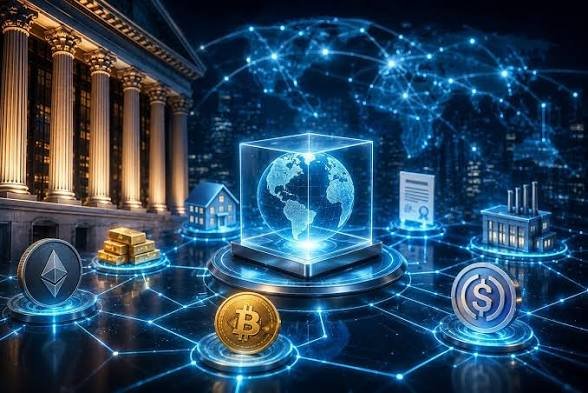
For years, blockchain was largely associated with cryptocurrencies and speculative digital assets. That picture is changing. This lead to Tokenized Finance.
In 2026, the more consequential development may be happening inside traditional finance, where banks, asset managers, financial-market infrastructures and central banks are exploring ways to represent money and financial assets as digital tokens. This shift is known as tokenization the representation of financial assets or liabilities on programmable digital ledgers.
The International Monetary Fund says tokenization could represent a structural change in financial architecture rather than simply another upgrade to existing financial technology. So, what comes next?
From Digital Records to Programmable Finance
Financial markets have already been highly digital for decades. Stocks, bonds and bank deposits are generally represented electronically. But tokenization goes a step further.
A tokenized asset can carry information about ownership and transfer directly through a digital infrastructure. Smart contracts can potentially automate parts of a transaction, while shared ledgers can reduce the need for multiple institutions to reconcile separate records.
The IMF identifies three characteristics that could make tokenized finance particularly significant: programmability, shared ledgers and atomic settlement.
In an atomic transaction, delivery of an asset and payment can occur simultaneously rather than through a sequence of separate processes. That could reduce settlement times and operational costs while allowing financial contracts to operate in more automated ways. But speed is not automatically the same as safety.
Tokenized Deposits, Stablecoins and Digital Money
One of the biggest questions concerns what actually settles transactions in a tokenized financial system. Several possibilities are emerging.
Tokenized bank deposits essentially represent existing commercial-bank liabilities in digital form. They could allow banks to combine conventional deposit money with programmable transactions. Stablecoins are privately issued digital tokens designed to maintain a stable value, usually by being backed by reserve assets.
They could make cross-border payments faster and potentially reduce remittance costs. Central bank digital money, including wholesale central bank digital currencies, could provide a digital settlement asset directly connected to central-bank money.
The IMF argues that each model allocates risks differently between the public and private sectors. This is why the future of tokenized finance is not simply a question of which technology wins. It is also a question of who provides trust, liquidity and oversight.
Stablecoins Could Become a Major Battleground
Stablecoins are currently among the most mature applications of tokenized finance. The IMF says financial institutions are experimenting with stablecoins, tokenized deposits, tokenized securities and money-market funds, while central banks are examining ways to incorporate tokenization into monetary and financial infrastructure.
Their potential is significant.Imagine sending money internationally without relying on multiple intermediaries, correspondent banks and settlement systems.
A programmable digital token could theoretically move across borders much faster. For migrant workers and their families, cheaper and faster remittances could be particularly important. But stablecoins also create risks.
The IMF warns that large-scale adoption could contribute to currency substitution, capital-flow volatility and pressure on monetary policy, particularly in emerging markets.
The Bank for International Settlements has similarly argued that stablecoins have useful applications but contain structural weaknesses that need to be addressed if they are to play a larger role in the monetary system.
Tokenized Securities Could Change Capital Markets
Another potentially important development is the tokenization of traditional financial assets. Bonds, money-market funds, equities and other securities could increasingly be issued or represented through tokenized infrastructures.
This could make ownership and transfers more programmable and potentially enable markets to operate with greater automation. For investors, the long-term attraction could include faster settlement, improved transparency and potentially greater access to certain assets.
For issuers, tokenization could create new ways of reaching investors and managing securities.However, the legal question remains crucial: Does a digital token legally represent ownership of the underlying asset? Without clear answers about ownership, settlement finality, investor protection and jurisdiction, tokenization could remain fragmented.
The IMF identifies legal certainty and governance as essential foundations for the technology.
The Biggest Challenge May Be Interoperability
A tokenized future will not work particularly well if every financial institution builds an isolated digital island.Imagine one bank using one ledger, another bank using a different system and a securities exchange operating on a third platform.
If those systems cannot communicate, the efficiency promised by tokenization could disappear. The European Central Bank has warned about the risk of incompatible platforms creating or deepening fragmentation in capital markets.
Current European efforts are therefore focused partly on developing infrastructure that can connect different digital financial systems while maintaining central-bank money at the core.
Interoperability may therefore become one of the defining issues of the next stage of digital finance.
Regulation Will Shape the Market
Technology alone will not determine how tokenized finance develops. Governments and financial regulators are increasingly examining stablecoins, digital securities, tokenized deposits, custody arrangements, cybersecurity and consumer protection.
The IMF argues that regulatory approaches across jurisdictions can diverge, creating opportunities for regulatory arbitrage. International coordination could therefore become increasingly important as tokenized assets move across borders.
The challenge for regulators will be finding a balance between allowing innovation and preventing new forms of financial instability. Too little regulation could create risks involving fraud, liquidity, cybersecurity and market manipulation.
Excessively fragmented regulation could make international digital finance difficult to scale.
Emerging Markets Face Both Opportunity and Risk
For developing economies, tokenization could provide an opportunity to modernize financial infrastructure. Countries with expensive payment systems could potentially use digital infrastructure to improve cross-border transfers.
Tokenized assets could also broaden access to financial markets and reduce some traditional settlement barriers. But there is another side. If foreign-currency stablecoins become widely used, people in countries with weaker currencies could increasingly hold and transact in foreign digital money.
The IMF warns that this could increase currency substitution and complicate monetary policy in some emerging economies.
That means countries will need to consider tokenization as both a technological opportunity and a macroeconomic issue. What Comes Next?The next phase of tokenized finance is unlikely to be defined by one revolutionary product.
Instead, the transformation may happen gradually through tokenized deposits, stablecoins, digital securities, programmable payments and new financial-market infrastructure.
The BIS has described the current transition as a gradual movement from experimentation toward more production-ready applications rather than a sudden “big bang.” The IMF similarly argues that the future is not predetermined.
One possible outcome is a coordinated system built around safe settlement assets, interoperable infrastructure and internationally aligned oversight. Another is a fragmented ecosystem containing incompatible platforms and digital silos. That makes the coming years particularly important.
Tokenized finance could make financial transactions faster, more programmable and potentially more accessible. But the technology also moves risk into new areas, software, infrastructure, liquidity management and digital governance.
Ultimately, the central question will not simply be whether finance becomes tokenized. It will be whether governments, financial institutions and technology providers can build a tokenized financial system that remains trustworthy, interoperable and resilient.
The technology is developing rapidly. The rules governing it are now racing to catch up.